Sep 3, 2026
International Migration in the UK
From 906k peak to 171k: ONS provisional May 2026 data shows UK net migration down 75% since early 2023. Non-EU work visas halved, EU & British net negative since 2022. What 2027 holds and what it means for brands targeting diverse Britain.
⏱ 9 min read
By Mediareach
At Mediareach, we're thrilled to share the latest insights on international migration trends in the UK, but the picture in 2026 looks radically different from just two years ago.
The UK has a rich history of welcoming people from all corners of the world, and international migration continues to enrich our society with new cultures, skills and talents. Yet according to the Office for National Statistics provisional estimates released 21 May 2026, the era of record-high net migration is over, at least for now.
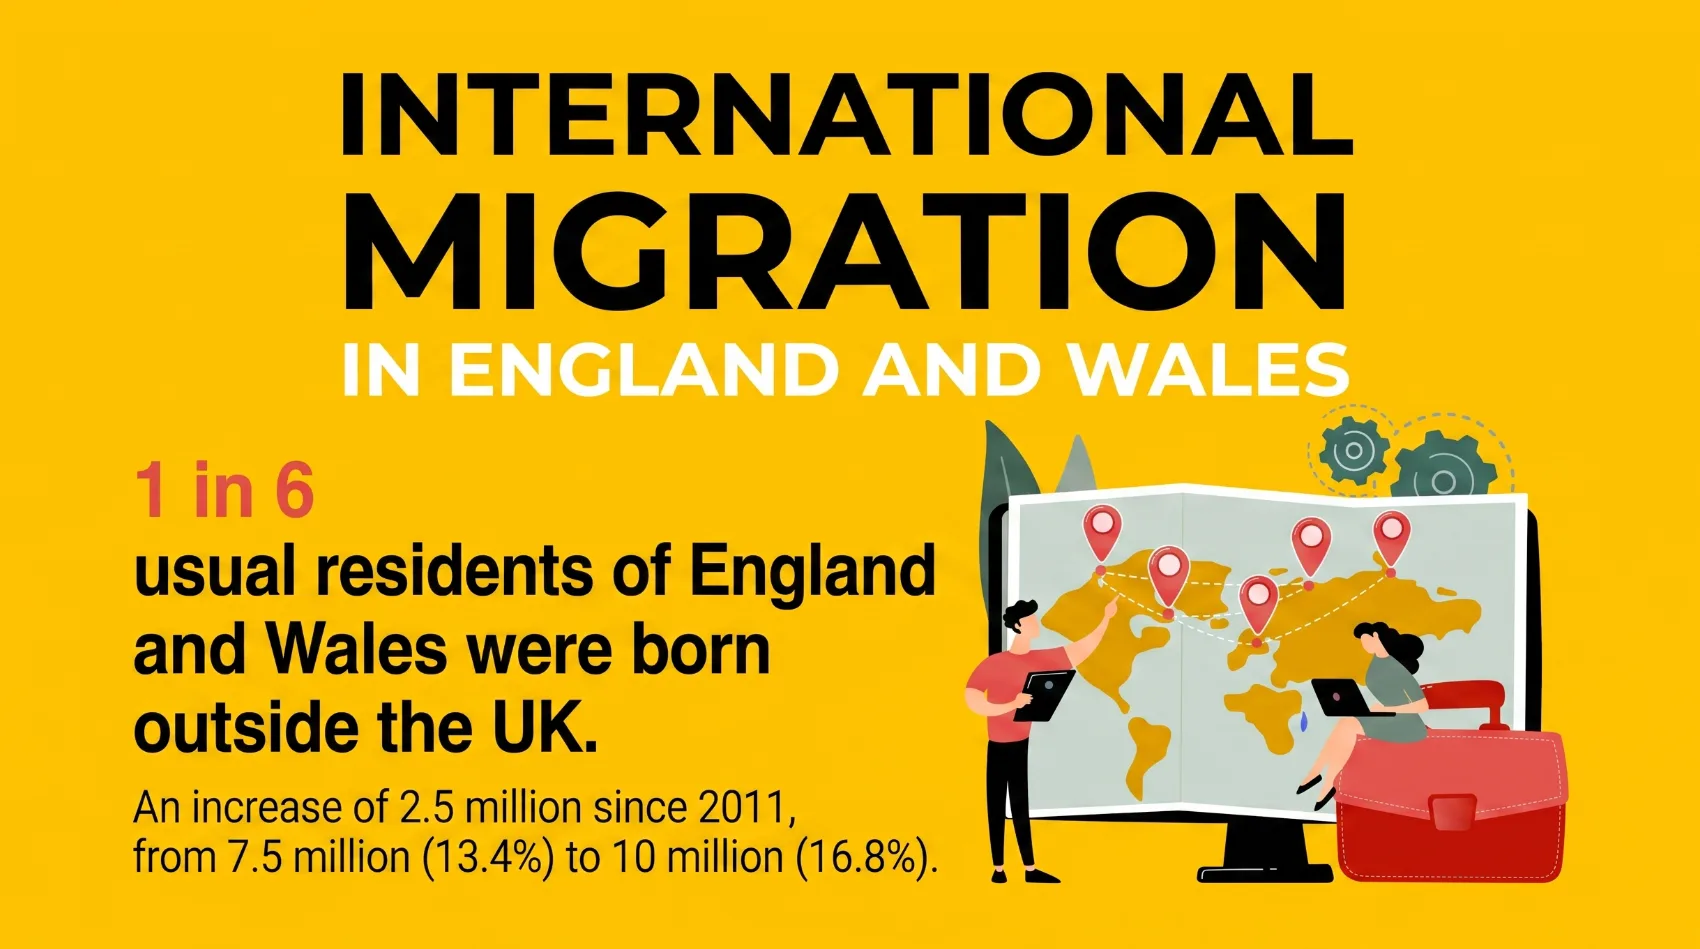
Latest Data May 2026: Net Migration Falls to 171,000
ONS long-term international migration (people moving for 12 months or more) shows:
171,000
Net Migration YE Dec 2025 (Provisional)
431,000
Net Migration YE Dec 2024 (Revised)
860k - 906k
Peak YE June 2023
-75%
Fall Since Peak Early 2023
YE Dec 2025: 171,000 net — down from 331,000 a year earlier (YE Dec 2024 originally estimated 431k, revised from earlier 345k). Nearly halved in 12 months.
YE June 2025: 204,000 net — down from 649,000 YE June 2024, lowest since early 2021 when new immigration system and Covid restrictions were in place.
YE Dec 2024: 431,000 — down 49.9% from 860,000 a year earlier, biggest calendar-year drop on record.
This means annual net migration is down by three-quarters of a million people since its peak in early 2023, notes Sarah Crofts, Deputy Director of Migration Statistics at ONS.
What's Driving the Collapse?
1. Non-EU Immigration, The Main Driver, Now Halved
Overall, non-EU net migration has fallen by two-thirds since it peaked in 2023. In the most recent period to Dec 2025, the number of people from outside the EU arriving for work-related reasons almost halved and is the main factor behind the continued fall. Student dependants collapsed after policy changes.
2. Policy Changes from Early 2024
Two waves of Home Office changes are biting:
May 2023: Most taught postgraduate students banned from bringing dependants
Dec 2023 - Apr 2024: Care workers banned from bringing dependants, social care firms must be CQC-registered to sponsor, skilled worker salary threshold raised (from £26,200 to £38,700), shortage occupation list reformed, minimum income for family visas raised to £29,000 rising to £38,700
Home Office estimated these would cut 300,000 arrivals in a hypothetical year. ONS data shows the impact arrived exactly as forecast from April 2024 onwards.
3. EU and British Net Migration Negative Since 2022
Both British and EU net migration is negative, more people leaving than arriving. EU net has been negative since 2022 after falling from +250k in 2016. British nationals net is broadly stable but negative, with new DWP-based methodology replacing the old International Passenger Survey showing more accurate exits via tax/benefits records. Around the world, young people move most, this is true for Brits leaving as well.
"Annual international net migration is down by three-quarters of a million people since its peak in early 2023. The fall in non-EU work immigration is the main driver."
ONS National Statistical Blog
2027 Forecast: Where Does UK Migration Go Next?
Despite the sharp fall, ONS and OBR do not expect net migration to stay at 171k.
ONS & OBR Central Forecast for 2027
In January 2024, ONS published updated long-term projections assuming net inflows follow a linear path downward from ~670,000 in mid-2023 to a medium-term level of 315,000 from 2027-28. This is 70,000 higher than the previous steady-state 245,000. It is based on 10-year historical average to mid-2023 and expert panel consultation (12 Dec 2023). OBR March 2026 Economic and Fiscal Outlook uses this 315k endpoint but expects a sharper near-term dip due to higher emigration of recent student arrivals and policy drag. OBR now expects ~350,000 average a year over next 5 years, settling at 315,000 by 2027-28. November 2025 OBR revision was more cautious: 235,000 average 2026-2030, down from 295,000 in Nov 2023 forecast, driven by more British emigration and lower labour participation of dependants.
Scenarios for 2027-28:
High migration scenario: 515,000 net in 2028-29 — GDP 1.5% higher than central forecast, GDP per person largely unchanged unless migrants are 90% work-visa participation (then +0.8% per person)
Central scenario: 315,000 net — ONS/OBR baseline, population +2.2M from migration mid-2024 to mid-2034 vs -450k natural change (deaths exceeding births)
Low migration scenario: 115,000 net in 2028-29 — symmetric negative impact, £5bn lower tax revenues by 2030 per IFS analysis
OBR notes: net migration remains the only source of UK population growth — from 69.3M mid-2024 to 73.7M projected by 2036. 73% of growth 2018-2028 was projected to be direct result of international migration, rising to 84% 2018-2048 per ONS 2018 projections.
What Does This Mean for Multicultural Marketing in 2026-2027?
At first glance, falling net migration might suggest a shrinking diverse audience. The opposite is true.
55% of the UK's population increase over the last 10 years has been due to migration. 4.5% rise from 66.4M to 69.4M 2018-2028, 2.2M of that from migration. But second and third generation communities are now the core: British Asian, Black British, Eastern European settled families, Arab British communities, many highly affluent, all permanent consumers.
1. Shift from New Arrivals to Settled Communities
With EU net negative and non-EU inflows lower, brands should pivot from targeting recent arrivals to second/third generation who drive spending power, festival commerce (Ramadan, Eid, Diwali, Vaisakhi, Chinese New Year, Nawrooz) and family decision-making.
2. Work, Study and Family Visas Still Drive Cultural Nuance
Even with dependant restrictions, work and study remain top reasons. Indian, Nigerian, Pakistani, Chinese and Filipino nationals dominate non-EU flows. Media habits, languages and trust channels differ sharply, requiring diaspora media planning, not just English mainstream.
3. British Emigration Creates Opportunity Abroad
Stable British emigration (Spain, Australia, US, France) and new data showing younger Brits leaving for work/study means UK brands with international footprint can follow audiences.
"Undercurrents of migration patterns have provided Britain with economic uplifts since World War 2, but what we are witnessing today is like nothing before. The multiculturalism of the UK is constantly evolving."
Mediareach Advertising Week Europe
Turn Migration Data into Growth Strategy
Net migration at 171k doesn't mean less diversity, it means more settled, more affluent, more influential multicultural communities. Mediareach's Multicultural Communities Report 2026 maps demographic trends, media landscape and spending power for 2027.
Sources & References
ONS, "Long-term international migration, provisional: year ending December 2025" — Released 21 May 2026. Net 171k YE Dec 2025, 331k year earlier. ons.gov.uk - YE Dec 2025
ONS National Statistical Blog, Sarah Crofts, "Net migration continues to fall" 21 May 2026 — 75% fall since early 2023 peak, non-EU work halved. blog.ons.gov.uk May 2026
ONS, "Long-term international migration, provisional: year ending December 2024" — Net 431k, down from 860k, 49.9% fall. ons.gov.uk - YE Dec 2024
ONS, "Long-term international migration, provisional: year ending June 2025" — Net 204k down from 649k YE June 2024. ons.gov.uk - YE June 2025
OBR, "Net migration forecast and its impact on the economy" — ONS projection 315k from 2027-28, 70k higher than 245k previous, linear path from 670k mid-2023. obr.uk
OBR Economic and Fiscal Outlook March 2026 — Average 350k over forecast, settling 315k 2027-28; scenarios 115k-515k. obr.uk March 2026
IFS / OBR November 2025 revision — 235k average 2026-2030 vs 295k Nov 2023, £5bn lower tax by 2030. ifs.org.uk
House of Commons Library Research Briefing 1 Dec 2025 — Net migration revision 345k YE Dec 2024 vs 431k. parliament.uk
ONS 2018 National Population Projections — 4.5% rise 66.4M to 69.4M, 73% from migration, 84% 2018-2048. ons.gov.uk
international migration UK 2026
ONS net migration 171k
UK migration forecast 2027
long-term international migration provisional
non-EU migration fall
EU net migration negative
British emigration
OBR migration forecast 315k
UK population growth migration
multicultural marketing migration
student dependant visa policy
UK immigration policy 2024
diverse communities UK
The UK's pioneering multicultural marketing and advertising agency. Over 40 years connecting brands with diverse communities through cultural insight, creative excellence, and intelligent media strategy. mediareach.co

Sep 3, 2026
International Migration in the UK
From 906k peak to 171k: ONS provisional May 2026 data shows UK net migration down 75% since early 2023. Non-EU work visas halved, EU & British net negative since 2022. What 2027 holds and what it means for brands targeting diverse Britain.
⏱ 9 min read
By Mediareach
At Mediareach, we're thrilled to share the latest insights on international migration trends in the UK, but the picture in 2026 looks radically different from just two years ago.
The UK has a rich history of welcoming people from all corners of the world, and international migration continues to enrich our society with new cultures, skills and talents. Yet according to the Office for National Statistics provisional estimates released 21 May 2026, the era of record-high net migration is over, at least for now.
Latest Data May 2026: Net Migration Falls to 171,000
ONS long-term international migration (people moving for 12 months or more) shows:
171,000
Net Migration YE Dec 2025 (Provisional)
431,000
Net Migration YE Dec 2024 (Revised)
860k - 906k
Peak YE June 2023
-75%
Fall Since Peak Early 2023
YE Dec 2025: 171,000 net — down from 331,000 a year earlier (YE Dec 2024 originally estimated 431k, revised from earlier 345k). Nearly halved in 12 months.
YE June 2025: 204,000 net — down from 649,000 YE June 2024, lowest since early 2021 when new immigration system and Covid restrictions were in place.
YE Dec 2024: 431,000 — down 49.9% from 860,000 a year earlier, biggest calendar-year drop on record.
This means annual net migration is down by three-quarters of a million people since its peak in early 2023, notes Sarah Crofts, Deputy Director of Migration Statistics at ONS.
What's Driving the Collapse?
1. Non-EU Immigration, The Main Driver, Now Halved
Overall, non-EU net migration has fallen by two-thirds since it peaked in 2023. In the most recent period to Dec 2025, the number of people from outside the EU arriving for work-related reasons almost halved and is the main factor behind the continued fall. Student dependants collapsed after policy changes.
2. Policy Changes from Early 2024
Two waves of Home Office changes are biting:
May 2023: Most taught postgraduate students banned from bringing dependants
Dec 2023 - Apr 2024: Care workers banned from bringing dependants, social care firms must be CQC-registered to sponsor, skilled worker salary threshold raised (from £26,200 to £38,700), shortage occupation list reformed, minimum income for family visas raised to £29,000 rising to £38,700
Home Office estimated these would cut 300,000 arrivals in a hypothetical year. ONS data shows the impact arrived exactly as forecast from April 2024 onwards.
3. EU and British Net Migration Negative Since 2022
Both British and EU net migration is negative, more people leaving than arriving. EU net has been negative since 2022 after falling from +250k in 2016. British nationals net is broadly stable but negative, with new DWP-based methodology replacing the old International Passenger Survey showing more accurate exits via tax/benefits records. Around the world, young people move most, this is true for Brits leaving as well.
"Annual international net migration is down by three-quarters of a million people since its peak in early 2023. The fall in non-EU work immigration is the main driver."
ONS National Statistical Blog
2027 Forecast: Where Does UK Migration Go Next?
Despite the sharp fall, ONS and OBR do not expect net migration to stay at 171k.
ONS & OBR Central Forecast for 2027
In January 2024, ONS published updated long-term projections assuming net inflows follow a linear path downward from ~670,000 in mid-2023 to a medium-term level of 315,000 from 2027-28. This is 70,000 higher than the previous steady-state 245,000. It is based on 10-year historical average to mid-2023 and expert panel consultation (12 Dec 2023). OBR March 2026 Economic and Fiscal Outlook uses this 315k endpoint but expects a sharper near-term dip due to higher emigration of recent student arrivals and policy drag. OBR now expects ~350,000 average a year over next 5 years, settling at 315,000 by 2027-28. November 2025 OBR revision was more cautious: 235,000 average 2026-2030, down from 295,000 in Nov 2023 forecast, driven by more British emigration and lower labour participation of dependants.
Scenarios for 2027-28:
High migration scenario: 515,000 net in 2028-29 — GDP 1.5% higher than central forecast, GDP per person largely unchanged unless migrants are 90% work-visa participation (then +0.8% per person)
Central scenario: 315,000 net — ONS/OBR baseline, population +2.2M from migration mid-2024 to mid-2034 vs -450k natural change (deaths exceeding births)
Low migration scenario: 115,000 net in 2028-29 — symmetric negative impact, £5bn lower tax revenues by 2030 per IFS analysis
OBR notes: net migration remains the only source of UK population growth — from 69.3M mid-2024 to 73.7M projected by 2036. 73% of growth 2018-2028 was projected to be direct result of international migration, rising to 84% 2018-2048 per ONS 2018 projections.
What Does This Mean for Multicultural Marketing in 2026-2027?
At first glance, falling net migration might suggest a shrinking diverse audience. The opposite is true.
55% of the UK's population increase over the last 10 years has been due to migration. 4.5% rise from 66.4M to 69.4M 2018-2028, 2.2M of that from migration. But second and third generation communities are now the core: British Asian, Black British, Eastern European settled families, Arab British communities, many highly affluent, all permanent consumers.
1. Shift from New Arrivals to Settled Communities
With EU net negative and non-EU inflows lower, brands should pivot from targeting recent arrivals to second/third generation who drive spending power, festival commerce (Ramadan, Eid, Diwali, Vaisakhi, Chinese New Year, Nawrooz) and family decision-making.
2. Work, Study and Family Visas Still Drive Cultural Nuance
Even with dependant restrictions, work and study remain top reasons. Indian, Nigerian, Pakistani, Chinese and Filipino nationals dominate non-EU flows. Media habits, languages and trust channels differ sharply, requiring diaspora media planning, not just English mainstream.
3. British Emigration Creates Opportunity Abroad
Stable British emigration (Spain, Australia, US, France) and new data showing younger Brits leaving for work/study means UK brands with international footprint can follow audiences.
"Undercurrents of migration patterns have provided Britain with economic uplifts since World War 2, but what we are witnessing today is like nothing before. The multiculturalism of the UK is constantly evolving."
Mediareach Advertising Week Europe
Turn Migration Data into Growth Strategy
Net migration at 171k doesn't mean less diversity, it means more settled, more affluent, more influential multicultural communities. Mediareach's Multicultural Communities Report 2026 maps demographic trends, media landscape and spending power for 2027.
Sources & References
ONS, "Long-term international migration, provisional: year ending December 2025" — Released 21 May 2026. Net 171k YE Dec 2025, 331k year earlier. ons.gov.uk - YE Dec 2025
ONS National Statistical Blog, Sarah Crofts, "Net migration continues to fall" 21 May 2026 — 75% fall since early 2023 peak, non-EU work halved. blog.ons.gov.uk May 2026
ONS, "Long-term international migration, provisional: year ending December 2024" — Net 431k, down from 860k, 49.9% fall. ons.gov.uk - YE Dec 2024
ONS, "Long-term international migration, provisional: year ending June 2025" — Net 204k down from 649k YE June 2024. ons.gov.uk - YE June 2025
OBR, "Net migration forecast and its impact on the economy" — ONS projection 315k from 2027-28, 70k higher than 245k previous, linear path from 670k mid-2023. obr.uk
OBR Economic and Fiscal Outlook March 2026 — Average 350k over forecast, settling 315k 2027-28; scenarios 115k-515k. obr.uk March 2026
IFS / OBR November 2025 revision — 235k average 2026-2030 vs 295k Nov 2023, £5bn lower tax by 2030. ifs.org.uk
House of Commons Library Research Briefing 1 Dec 2025 — Net migration revision 345k YE Dec 2024 vs 431k. parliament.uk
ONS 2018 National Population Projections — 4.5% rise 66.4M to 69.4M, 73% from migration, 84% 2018-2048. ons.gov.uk
international migration UK 2026
ONS net migration 171k
UK migration forecast 2027
long-term international migration provisional
non-EU migration fall
EU net migration negative
British emigration
OBR migration forecast 315k
UK population growth migration
multicultural marketing migration
student dependant visa policy
UK immigration policy 2024
diverse communities UK
The UK's pioneering multicultural marketing and advertising agency. Over 40 years connecting brands with diverse communities through cultural insight, creative excellence, and intelligent media strategy. mediareach.co
Sep 3, 2026
International Migration in the UK
From 906k peak to 171k: ONS provisional May 2026 data shows UK net migration down 75% since early 2023. Non-EU work visas halved, EU & British net negative since 2022. What 2027 holds and what it means for brands targeting diverse Britain.
⏱ 9 min read
By Mediareach
At Mediareach, we're thrilled to share the latest insights on international migration trends in the UK, but the picture in 2026 looks radically different from just two years ago.
The UK has a rich history of welcoming people from all corners of the world, and international migration continues to enrich our society with new cultures, skills and talents. Yet according to the Office for National Statistics provisional estimates released 21 May 2026, the era of record-high net migration is over, at least for now.
Latest Data May 2026: Net Migration Falls to 171,000
ONS long-term international migration (people moving for 12 months or more) shows:
171,000
Net Migration YE Dec 2025 (Provisional)
431,000
Net Migration YE Dec 2024 (Revised)
860k - 906k
Peak YE June 2023
-75%
Fall Since Peak Early 2023
YE Dec 2025: 171,000 net — down from 331,000 a year earlier (YE Dec 2024 originally estimated 431k, revised from earlier 345k). Nearly halved in 12 months.
YE June 2025: 204,000 net — down from 649,000 YE June 2024, lowest since early 2021 when new immigration system and Covid restrictions were in place.
YE Dec 2024: 431,000 — down 49.9% from 860,000 a year earlier, biggest calendar-year drop on record.
This means annual net migration is down by three-quarters of a million people since its peak in early 2023, notes Sarah Crofts, Deputy Director of Migration Statistics at ONS.
What's Driving the Collapse?
1. Non-EU Immigration, The Main Driver, Now Halved
Overall, non-EU net migration has fallen by two-thirds since it peaked in 2023. In the most recent period to Dec 2025, the number of people from outside the EU arriving for work-related reasons almost halved and is the main factor behind the continued fall. Student dependants collapsed after policy changes.
2. Policy Changes from Early 2024
Two waves of Home Office changes are biting:
May 2023: Most taught postgraduate students banned from bringing dependants
Dec 2023 - Apr 2024: Care workers banned from bringing dependants, social care firms must be CQC-registered to sponsor, skilled worker salary threshold raised (from £26,200 to £38,700), shortage occupation list reformed, minimum income for family visas raised to £29,000 rising to £38,700
Home Office estimated these would cut 300,000 arrivals in a hypothetical year. ONS data shows the impact arrived exactly as forecast from April 2024 onwards.
3. EU and British Net Migration Negative Since 2022
Both British and EU net migration is negative, more people leaving than arriving. EU net has been negative since 2022 after falling from +250k in 2016. British nationals net is broadly stable but negative, with new DWP-based methodology replacing the old International Passenger Survey showing more accurate exits via tax/benefits records. Around the world, young people move most, this is true for Brits leaving as well.
"Annual international net migration is down by three-quarters of a million people since its peak in early 2023. The fall in non-EU work immigration is the main driver."
ONS National Statistical Blog
2027 Forecast: Where Does UK Migration Go Next?
Despite the sharp fall, ONS and OBR do not expect net migration to stay at 171k.
ONS & OBR Central Forecast for 2027
In January 2024, ONS published updated long-term projections assuming net inflows follow a linear path downward from ~670,000 in mid-2023 to a medium-term level of 315,000 from 2027-28. This is 70,000 higher than the previous steady-state 245,000. It is based on 10-year historical average to mid-2023 and expert panel consultation (12 Dec 2023). OBR March 2026 Economic and Fiscal Outlook uses this 315k endpoint but expects a sharper near-term dip due to higher emigration of recent student arrivals and policy drag. OBR now expects ~350,000 average a year over next 5 years, settling at 315,000 by 2027-28. November 2025 OBR revision was more cautious: 235,000 average 2026-2030, down from 295,000 in Nov 2023 forecast, driven by more British emigration and lower labour participation of dependants.
Scenarios for 2027-28:
High migration scenario: 515,000 net in 2028-29 — GDP 1.5% higher than central forecast, GDP per person largely unchanged unless migrants are 90% work-visa participation (then +0.8% per person)
Central scenario: 315,000 net — ONS/OBR baseline, population +2.2M from migration mid-2024 to mid-2034 vs -450k natural change (deaths exceeding births)
Low migration scenario: 115,000 net in 2028-29 — symmetric negative impact, £5bn lower tax revenues by 2030 per IFS analysis
OBR notes: net migration remains the only source of UK population growth — from 69.3M mid-2024 to 73.7M projected by 2036. 73% of growth 2018-2028 was projected to be direct result of international migration, rising to 84% 2018-2048 per ONS 2018 projections.
What Does This Mean for Multicultural Marketing in 2026-2027?
At first glance, falling net migration might suggest a shrinking diverse audience. The opposite is true.
55% of the UK's population increase over the last 10 years has been due to migration. 4.5% rise from 66.4M to 69.4M 2018-2028, 2.2M of that from migration. But second and third generation communities are now the core: British Asian, Black British, Eastern European settled families, Arab British communities, many highly affluent, all permanent consumers.
1. Shift from New Arrivals to Settled Communities
With EU net negative and non-EU inflows lower, brands should pivot from targeting recent arrivals to second/third generation who drive spending power, festival commerce (Ramadan, Eid, Diwali, Vaisakhi, Chinese New Year, Nawrooz) and family decision-making.
2. Work, Study and Family Visas Still Drive Cultural Nuance
Even with dependant restrictions, work and study remain top reasons. Indian, Nigerian, Pakistani, Chinese and Filipino nationals dominate non-EU flows. Media habits, languages and trust channels differ sharply, requiring diaspora media planning, not just English mainstream.
3. British Emigration Creates Opportunity Abroad
Stable British emigration (Spain, Australia, US, France) and new data showing younger Brits leaving for work/study means UK brands with international footprint can follow audiences.
"Undercurrents of migration patterns have provided Britain with economic uplifts since World War 2, but what we are witnessing today is like nothing before. The multiculturalism of the UK is constantly evolving."
Mediareach Advertising Week Europe
Turn Migration Data into Growth Strategy
Net migration at 171k doesn't mean less diversity, it means more settled, more affluent, more influential multicultural communities. Mediareach's Multicultural Communities Report 2026 maps demographic trends, media landscape and spending power for 2027.
Sources & References
ONS, "Long-term international migration, provisional: year ending December 2025" — Released 21 May 2026. Net 171k YE Dec 2025, 331k year earlier. ons.gov.uk - YE Dec 2025
ONS National Statistical Blog, Sarah Crofts, "Net migration continues to fall" 21 May 2026 — 75% fall since early 2023 peak, non-EU work halved. blog.ons.gov.uk May 2026
ONS, "Long-term international migration, provisional: year ending December 2024" — Net 431k, down from 860k, 49.9% fall. ons.gov.uk - YE Dec 2024
ONS, "Long-term international migration, provisional: year ending June 2025" — Net 204k down from 649k YE June 2024. ons.gov.uk - YE June 2025
OBR, "Net migration forecast and its impact on the economy" — ONS projection 315k from 2027-28, 70k higher than 245k previous, linear path from 670k mid-2023. obr.uk
OBR Economic and Fiscal Outlook March 2026 — Average 350k over forecast, settling 315k 2027-28; scenarios 115k-515k. obr.uk March 2026
IFS / OBR November 2025 revision — 235k average 2026-2030 vs 295k Nov 2023, £5bn lower tax by 2030. ifs.org.uk
House of Commons Library Research Briefing 1 Dec 2025 — Net migration revision 345k YE Dec 2024 vs 431k. parliament.uk
ONS 2018 National Population Projections — 4.5% rise 66.4M to 69.4M, 73% from migration, 84% 2018-2048. ons.gov.uk
international migration UK 2026
ONS net migration 171k
UK migration forecast 2027
long-term international migration provisional
non-EU migration fall
EU net migration negative
British emigration
OBR migration forecast 315k
UK population growth migration
multicultural marketing migration
student dependant visa policy
UK immigration policy 2024
diverse communities UK
The UK's pioneering multicultural marketing and advertising agency. Over 40 years connecting brands with diverse communities through cultural insight, creative excellence, and intelligent media strategy. mediareach.co